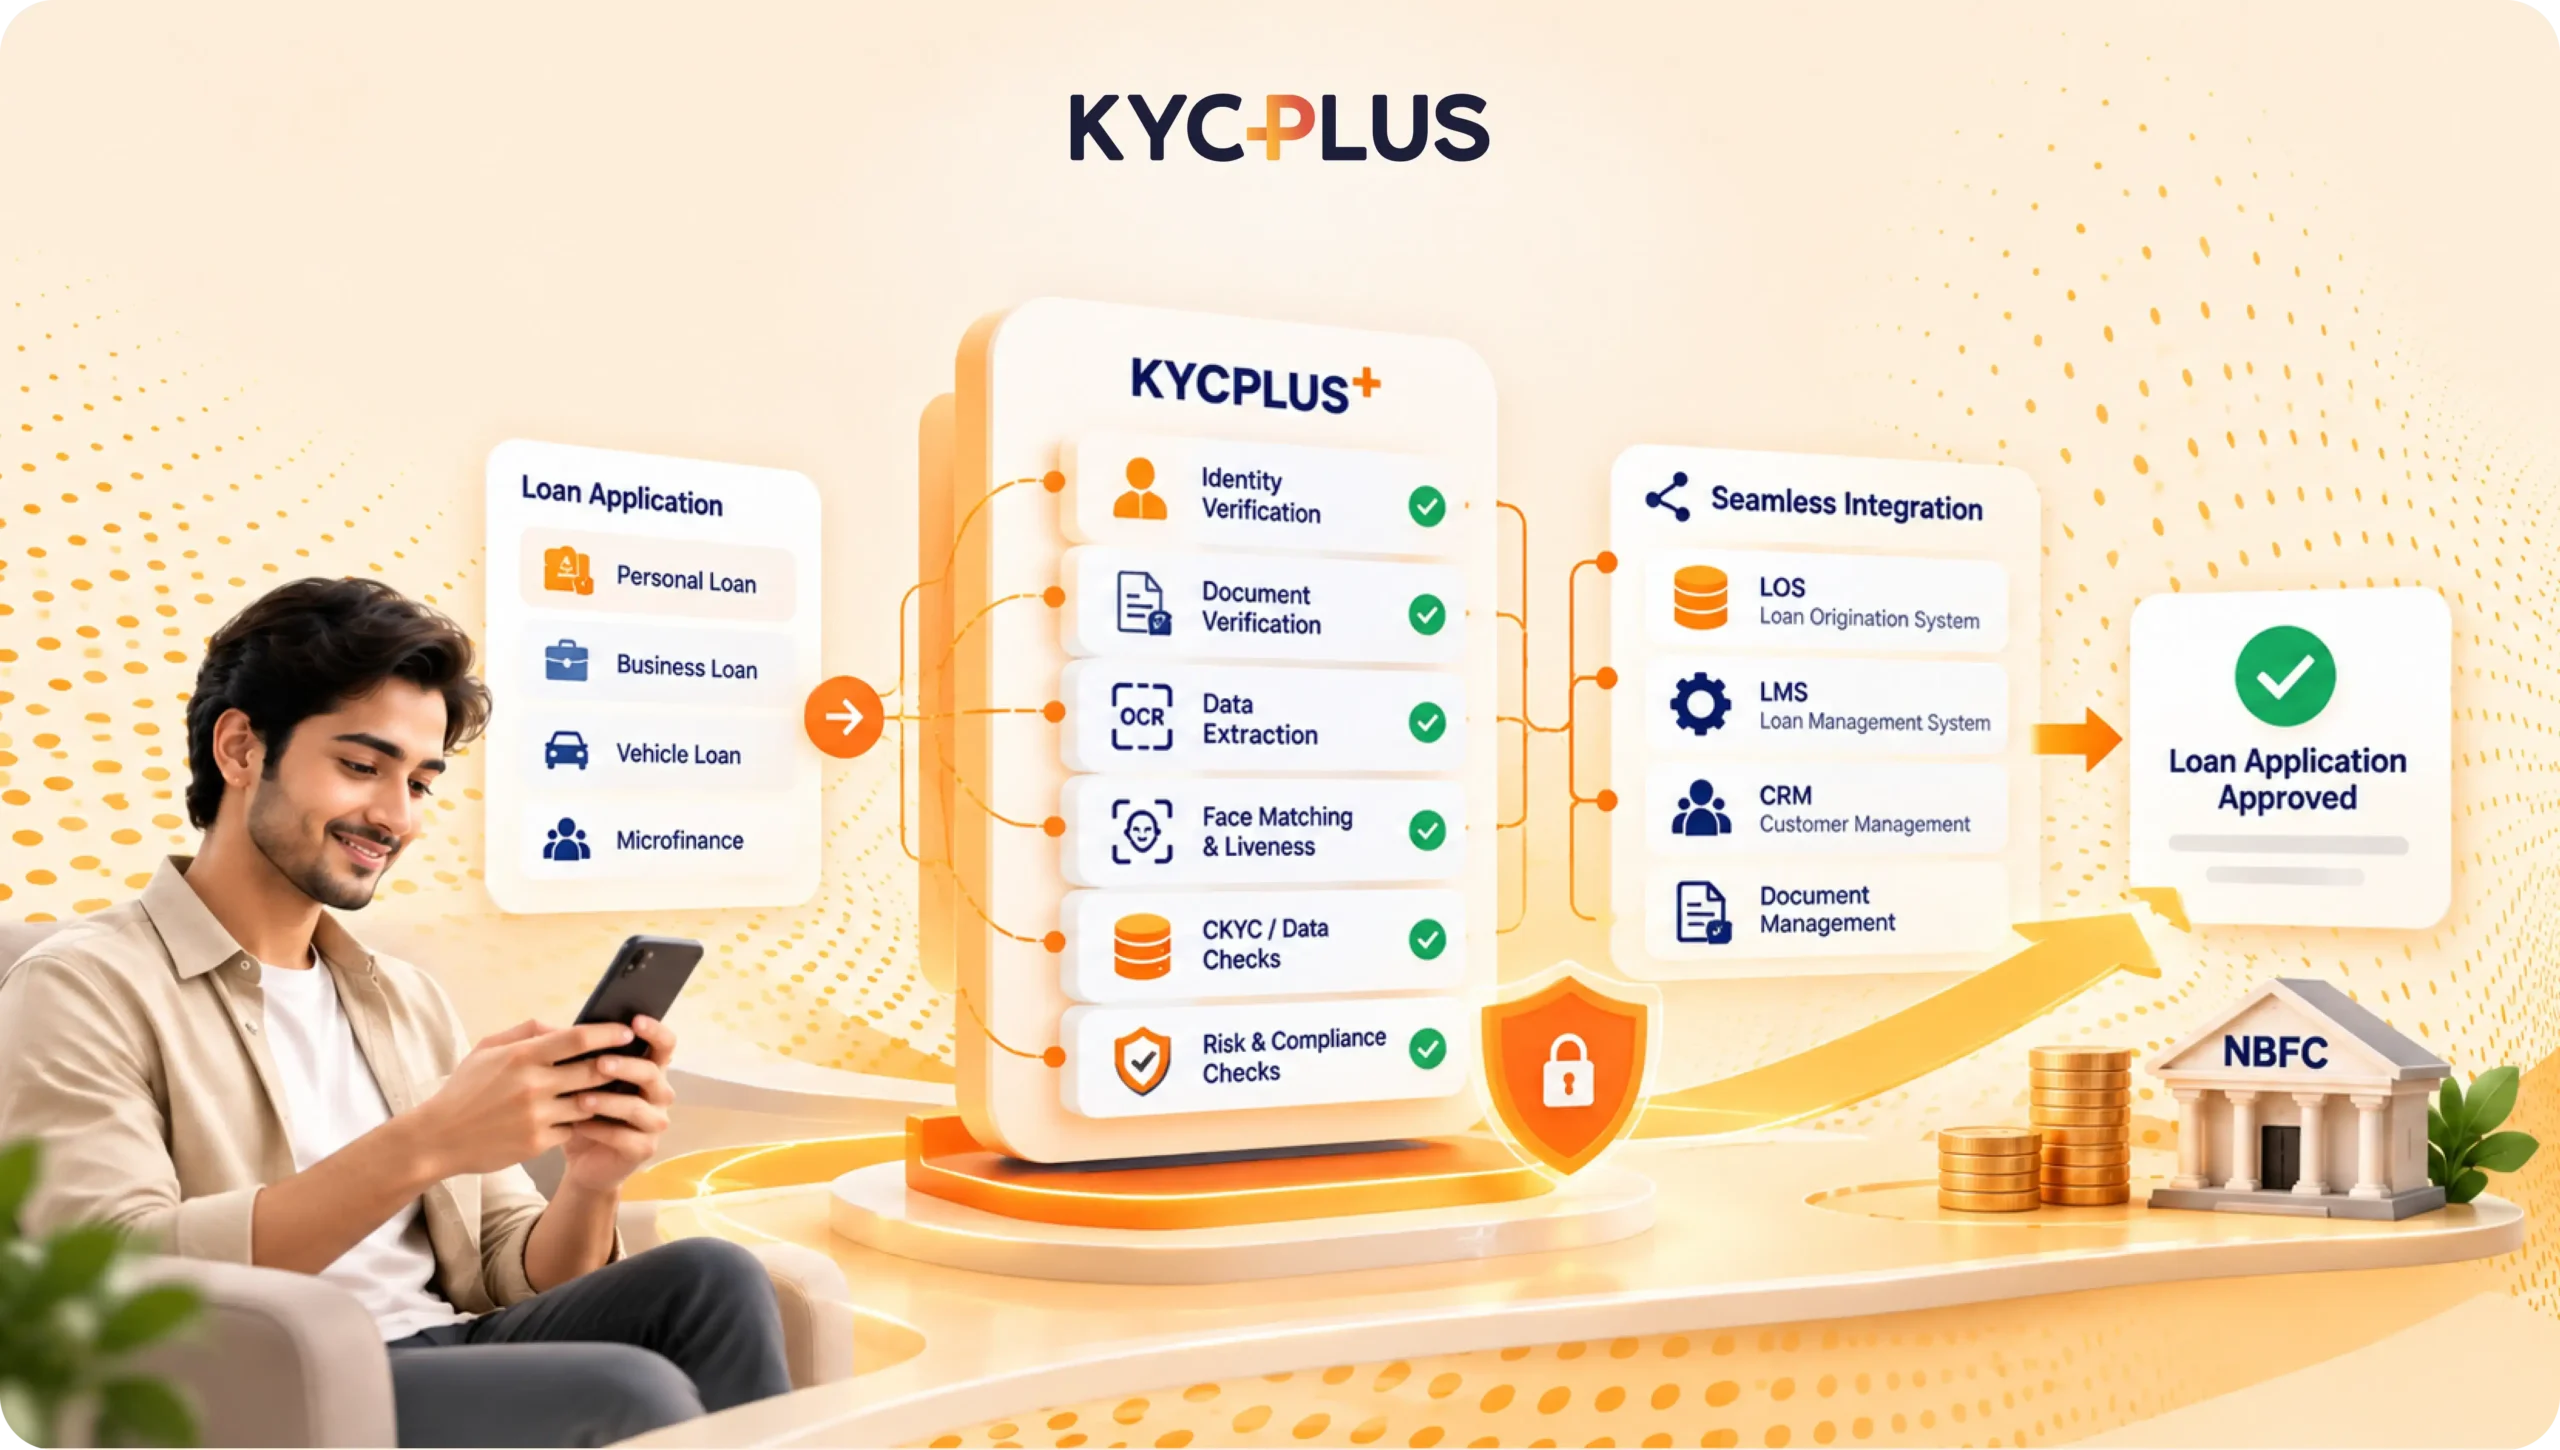
Non-Banking Financial Companies (NBFCs) play an important role in India’s financial services ecosystem. They provide lending, asset financing, consumer finance, business loans, vehicle loans, microfinance, and other financial services to individuals and businesses. As more NBFCs adopt digital lending and online customer onboarding, verifying customer identity efficiently has become an important operational requirement. Choosing the best KYC software for NBFCs in India can help streamline customer verification, improve onboarding efficiency, maintain accurate customer records, support secure document handling, and manage appropriate compliance controls. With reliable verification workflows, NBFCs can deliver a smoother application experience while addressing their operational and regulatory requirements.
Traditional KYC solution processes often involve manual document collection, repetitive data entry, disconnected applications, and employee-led verification. These activities can become difficult to manage as application volumes increase.
Modern KYC software can help NBFCs collect customer information digitally, process identity documents, integrate with authorized verification services, automate workflows, and maintain records of relevant activities.
Depending on the platform and implementation, these capabilities may include OCR-based data extraction, document verification, face matching, liveness detection, CKYC-related workflows, Re-KYC management, API integration, and centralized reporting.
However, selecting the right software requires more than comparing features. NBFCs need to consider their lending model, customer volume, technology infrastructure, regulatory obligations, data security requirements, and future growth plans.
This guide explains how KYC software works, why NBFCs need it, which features matter most, how to integrate it with lending systems, and what to evaluate before choosing a technology provider.
What Is KYC Software for NBFCs?
KYC stands for Know Your Customer. It refers to processes used to identify and verify customers and collect relevant information according to applicable legal and regulatory requirements.
KYC software helps NBFCs manage these processes through digital applications, verification integrations, document processing, and workflow automation.
Instead of depending entirely on manual checks, an NBFC can use software to collect customer information, process documents, perform configured verification checks, and track the status of each application.
For example, a customer applying for a personal loan through an NBFC’s mobile application may need to submit identity information and supporting documents. The KYC platform can process the submitted information, perform supported checks, and transfer relevant results to the NBFC’s Loan Origination System (LOS).
The exact process depends on the NBFC’s business model, applicable requirements, and the software’s capabilities.
The Best KYC Software for NBFCs in India should therefore support more than document uploads. It should help the organization establish a structured, secure, and manageable customer verification process.
NBFCs may onboard customers through branches, websites, mobile applications, agents, business correspondents, and partner platforms.
Managing KYC consistently across these channels can be challenging.
Manual verification can require employees to review documents, enter information, and update multiple applications.
Digital workflows can reduce repetitive work and allow routine cases to move through configured verification steps more efficiently.
Actual processing time depends on the checks required, system integrations, document quality, and the number of cases needing manual review.
Employees may need to enter customer names, addresses, dates of birth, and document details manually.
OCR can extract supported fields from documents and send them into validation workflows, reducing repeated typing.
Different branches or teams may follow different manual procedures.
Centralized software can standardize data collection, validation rules, approval workflows, and status tracking.
A digital platform can show which applications are completed, pending, failed, or awaiting manual review.
This makes it easier for operations teams to identify delays.
As an NBFC expands into new markets or introduces new lending products, application volumes may rise.
Automation can help manage higher volumes without requiring every step to be performed manually.
A well-designed digital process can provide clear instructions, mobile-friendly document submission, and fewer unnecessary handoffs.
For customers applying for loans online, a smoother verification journey can make the overall application process easier to complete.
These are important reasons why NBFCs evaluate the Best KYC Software for NBFCs in India as part of their digital transformation plans.
The right feature set depends on the NBFC’s products, customer categories, and verification requirements. The following capabilities are worth evaluating.
Digital onboarding allows customers to complete the relevant application and identity verification steps through a website, mobile application, or other digital channel.
The software should provide structured data fields, clear instructions, and suitable document-upload functionality.
It should also support the NBFC’s existing customer journey rather than forcing the company to redesign every application process.
Identity document verification helps the NBFC assess the submitted documents according to configured validation checks.
Depending on the solution, these checks may include document readability, field consistency, supported authenticity indicators, and format validation.
Automated checks cannot guarantee that every fraudulent document will be detected. Additional verification or human review may still be required.
Optical Character Recognition converts supported document images into machine-readable information.
For example, OCR may extract a customer’s name, date of birth, address, or document number from supported documents.
The extracted information can then be compared with the details entered by the customer.
This can reduce manual data entry and help standardize information before it moves into the lending workflow.
Face matching compares facial information from two images, such as a selfie and an authorized reference photograph.
When appropriate for the use case, this can provide an additional verification signal.
NBFCs should evaluate accuracy, false matches, accessibility, privacy implications, and the process for handling inconclusive results.
Liveness detection helps assess whether a facial capture appears to come from a live person rather than a static image or another presentation attempt.
The technology can support remote verification, but effectiveness depends on the method and implementation.
It should be evaluated as one component of a broader verification process rather than a guarantee against identity fraud.
Central Know Your Customer (CKYC) is a centralized KYC framework relevant to applicable financial institutions and processes in India.
Where applicable, a digital platform may support workflows for CKYC search, retrieval, processing, and relevant record updates.
NBFCs should confirm that the provider supports the required workflow and authorized access arrangements.
CKYC processing should not be confused with operating the centralized registry itself.
Customer information may need to be reviewed or updated during the customer lifecycle, depending on the applicable framework and customer category.
A KYC platform with Re-KYC capabilities can help manage notifications, information collection, document updates, verification, and status tracking.
APIs allow the KYC platform to exchange information with the NBFC’s other applications.
Important integrations may include:
API integration reduces disconnected workflows and repetitive data transfers.
A centralized Document Management System can organize customer documents and make them easier for authorized employees to retrieve.
Useful features may include document indexing, categorization, search, access controls, and retention management.
The platform should maintain appropriate records of relevant activities.
Depending on the implementation, these can include timestamps, user actions, status changes, verification outcomes, and approval history.
Dashboards can show completed applications, pending cases, exceptions, and processing trends.
When comparing the Best KYC Software for NBFCs in India, NBFCs should evaluate the complete workflow rather than focusing only on individual verification features.
Digital lending NBFCs depend on online applications and technology-driven operations.
Customers may apply through mobile applications, websites, partner platforms, or digital marketplaces.
A typical onboarding journey can involve:
1. Customer registration.
2. Collection of required information.
3. Document submission.
4. OCR and data validation.
5. Applicable identity verification.
6. CKYC-related processing where relevant.
7. Manual review for cases requiring additional checks.
8. Transfer of relevant information to the LOS.
9. Continuation of the loan application workflow.
The KYC process and credit underwriting process serve different purposes. Identity verification does not automatically establish creditworthiness or guarantee loan approval.
A well-integrated KYC platform can help the NBFC complete identity-related tasks while keeping the lending decision process within the appropriate system.
For digital lending businesses, the Best KYC Software for NBFCs in India should provide reliable integrations and clear handling of failed, pending, and inconclusive verification cases.
Personal loan and consumer finance NBFCs may process large numbers of applications through digital channels.
The verification workflow needs to be efficient without overlooking the checks required for the relevant product and customer category.
A consistent workflow can reduce repetitive work for operations teams.
It can also make it easier to identify applications that need additional information or manual review.
Vehicle finance businesses may onboard customers through branches, dealerships, agents, and partner channels.
This creates a need for consistent document collection and verification across different points of customer acquisition.
A digital KYC platform can help standardize the process regardless of where the application originates.
For example, information collected through a dealership’s application interface may be transferred to the NBFC’s onboarding system through a secure integration.
The KYC workflow can then process the required customer information and supporting documents.
Vehicle finance NBFCs should evaluate whether the solution can support their channel structure, document requirements, integration needs, and application volumes.
Microfinance and small-ticket lending businesses may operate across geographically distributed locations and customer acquisition channels.
Employees or authorized representatives may collect customer information through assisted digital processes.
A suitable KYC platform can provide structured data capture, document processing, verification workflows, and centralized monitoring.
Mobile-friendly interfaces can be especially useful when field teams need to capture information outside a traditional office environment.
NBFCs should also assess connectivity requirements, device security, employee permissions, and procedures for handling incomplete submissions.
The Best KYB Verification for NBFCs in India should fit the actual operating environment rather than assuming every customer will complete onboarding independently through a smartphone.
OCR can reduce repetitive work in document-heavy verification processes.
Without OCR, an employee may have to read each document and manually enter information into the NBFC’s system.
With OCR, the platform can extract supported information and send it into a validation workflow.
A simplified process is:
Document Upload → OCR → Data Extraction → Field Validation → Verification Workflow → Customer Record
For example, if the customer’s submitted information differs from the information extracted from a document, the system can flag the mismatch for correction or review.
However, extraction accuracy depends on image quality, document format, language, and the capabilities of the OCR engine.
NBFCs should test the software using realistic document samples before deploying it across all channels.
OCR is a data-extraction technology, not independent proof of identity. It should be combined with appropriate verification checks.
Remote onboarding can create risks because the NBFC may not interact with the applicant face-to-face.
Face matching and liveness detection can provide additional signals within suitable digital verification workflows.
Facial matching compares an image captured during onboarding with an available reference photograph.
The result can help determine whether further review is needed.
Liveness detection helps assess whether a facial capture represents a live person rather than a static photograph or another presentation attempt.
Before selecting these features, NBFCs should examine:
These capabilities can strengthen a verification workflow when used appropriately, but they should not be treated as a complete fraud-prevention system by themselves.
KYC management may continue after the customer has completed the initial onboarding process.
Depending on applicable requirements, NBFCs may need to review or update customer information during the relationship.
CKYC-related processing and Re-KYC solution workflows can be incorporated into a broader KYC technology platform.
Potential activities include:
These capabilities can help NBFCs manage KYC operations in a more structured manner.
However, CKYC and Re-KYC are not interchangeable. Their roles and applicable processes differ, and the platform must support the requirements relevant to the institution.
When evaluating the Best KYC Software for NBFCs in India, organizations should confirm the
exact CKYC and Re-KYC capabilities available.
KYC software becomes more useful when it connects with the NBFC’s existing technology infrastructure.
A Loan Origination System typically manages application-related processes, while a Loan Management System supports loan servicing and related post-disbursement activities.
A CRM manages customer and relationship information.
A Core Banking System may be relevant depending on the institution’s operating model.
The KYC platform serves a different purpose: managing identity verification, KYC documents, and related workflows.
Customer Application → KYC Platform → Verification Result → LOS → Underwriting Workflow → Loan Decision
The KYC platform can also exchange relevant customer information with a CRM, customer database, document repository, or other authorized systems.
During implementation, technology teams should define:
Integration quality can have a significant impact on the overall onboarding experience.
Therefore, API capabilities should be a major evaluation criterion when selecting the Best KYC Software for NBFCs in India.
Manual KYC often involves several disconnected activities.
An employee collects documents, checks the submitted information, enters data into applications, tracks the status, and maintains records.
As application volumes increase, this approach can become difficult to manage.
Automated KYC introduces structured workflows that reduce repetitive work.
Customer Application → Employee Review → Manual Data Entry → Separate Verification Tools → Manual Tracking
Customer Application → Digital Data Capture → OCR and Validation → Configured Verification → Exception Handling → Integrated Customer Record
The digital process can improve consistency and visibility, but automation does not eliminate every manual review.
Cases with mismatched information, poor-quality documents, or inconclusive results may still require employee intervention.
The goal is to automate routine activities while maintaining appropriate controls for exceptional cases.
NBFCs should therefore examine security and privacy controls before selecting a provider.
The platform should allow administrators to assign permissions based on job responsibilities.
Sensitive information should be protected through suitable encryption mechanisms during transmission and, where appropriate, at rest.
API connections should use appropriate authentication, authorization, and protective controls.
The organization should understand where data is stored, how long it is retained, and how deletion or archival requirements are handled.
Relevant actions should be logged to support monitoring, investigations, and applicable audit requirements.
NBFCs should assess hosting arrangements, vulnerability management, backup processes, recovery plans, and incident response procedures.
The provider’s security documentation, contractual commitments, subprocessors, and incident notification procedures should be reviewed.
The applicable requirements will depend on the NBFC’s regulatory status and business activities.
The Best KYC Software for NBFCs in India should provide security controls that can be evaluated and tested, rather than relying only on general claims about being secure or compliant.
NBFCs in India must identify and follow the KYC and related requirements applicable to their particular regulatory status and activities.
The relevant process may depend on factors such as:
Where RBI requirements apply, the NBFC should review the relevant RBI KYC directions and other applicable rules.
Technology providers can help implement workflows, verification integrations, and recordkeeping processes, but software alone does not guarantee regulatory compliance.
The NBFC remains responsible for determining its obligations and ensuring that its actual processes meet them.
Before deployment, compliance and technology teams should work together to document the required checks, approval rules, exception handling, and record-retention policies.
Selecting KYC software is an important operational and technology decision. The best solution is the one that fits the NBFC’s specific use case, not necessarily the one with the longest feature list.
Identify whether the NBFC primarily offers personal loans, vehicle finance, business loans, microfinance, consumer finance, or other services.
Different models may require different customer journeys and document workflows.
List the checks required for your customer categories and products.
Confirm which capabilities are available natively and which require third-party integrations.
Review API documentation, test environments, error handling, integration support, and compatibility with your LOS, LMS, CRM, and other systems.
Consider daily application volumes, peak traffic, expected growth, and bulk-processing requirements.
Assess authentication, access management, encryption, audit logs, data retention, infrastructure, and incident response.
Check setup charges, transaction fees, recurring costs, integration expenses, support charges, and the cost of optional verification services.
Compare the total cost of ownership rather than only the initial quote.
Ask how the software handles failed documents, mismatched fields, inconclusive checks, service downtime, and cases requiring manual review.
Ensure that the platform provides useful operational dashboards and reports.
Understand who will manage integration, testing, deployment, training, and ongoing support.
Test the platform with representative customer journeys and document types.
Measure processing time, exception rates, integration reliability, and operational effort.
This structured approach can help NBFCs choose the Best KYC Software for NBFCs in India based on evidence rather than assumptions.
Even a capable software platform can create difficulties if implementation is not planned properly.
Older applications may not support modern integration methods.
A technical assessment can help determine whether APIs, middleware, or other integration mechanisms are required.
Existing customer records may contain incomplete or inconsistent information.
Data cleaning and validation can improve the quality of information entering the KYC workflow.
Blurry photographs, cropped documents, and unsupported file formats can reduce processing accuracy.
Clear customer instructions and image-quality checks can help address this issue.
Poorly configured workflows may route too many cases for manual review.
NBFCs should analyze exception reasons and improve the process without removing necessary verification controls.
Employees may need training to understand new workflows.
User-friendly interfaces, clear procedures, and structured training can improve adoption.
Some verification capabilities may depend on external services.
The NBFC should define service expectations, contingency procedures, monitoring, and escalation processes.
NBFCs should evaluate whether a KYC platform produces measurable improvements in operations.
Useful metrics include:
Calculate the cost of verification, software, and related operational work divided by the number of completed cases.
Measure how many customers complete the required onboarding journey.
Track the time taken from application submission to verification completion or a final decision.
Measure the percentage of cases requiring employee intervention.
Track cases involving missing information, mismatches, poor-quality documents, or technical failures.
Measure how many applicants abandon the onboarding process before completion.
Assess how many cases employees can handle while maintaining required quality and controls.
An NBFC can compare these metrics before and after implementation to understand the impact of automation.
However, ROI should include more than faster processing. Security, verification quality, customer experience, integration costs, and ongoing vendor charges also matter.
NBFCs may choose different deployment models depending on their infrastructure, policies, and requirements.
Cloud deployment can provide flexible capacity and reduce the need to manage all infrastructure internally.
It may be useful for NBFCs expecting fluctuating application volumes.
The organization must still assess data handling, hosting arrangements, security, contractual obligations, and applicable regulatory requirements.
On-premises deployment runs within infrastructure managed by the institution or its designated environment.
It may suit organizations with specific internal infrastructure requirements, although the NBFC may need to manage more maintenance and operational responsibilities.
A hybrid architecture can combine internal applications with selected cloud-based or external verification services.
The appropriate model depends on the NBFC’s technology environment, security assessment, and operating requirements.
Artificial intelligence can support document classification, data extraction, image-quality assessment, anomaly detection, and workflow prioritization.
For example, an AI-enabled document processing system may identify a document type and route it to the appropriate extraction process.
A platform may also flag unusual or inconsistent information for further review.
However, AI systems can produce errors and should be evaluated for accuracy, reliability, bias, and suitability for their intended use.
NBFCs should understand which decisions are automated, which results are advisory, and where employee review is required.
AI should strengthen the KYC process while preserving appropriate controls.
As these technologies mature, the Best KYC Software for NBFCs in India may increasingly combine AI, OCR, APIs, and workflow automation.
NBFCs evaluating digital KYC technology can consider specialized platforms such as KYCPLUS.
KYCPLUS is designed to support digital KYC, customer onboarding, CKYC-related workflows, Re-KYC, document management, and connected verification processes.
Depending on the implementation and required integrations, capabilities can include:
The value of an integrated platform lies in connecting these activities instead of managing every process in a separate application.
For example, an NBFC may collect customer information through its digital lending application, connect that application to KYCPLUS, process the configured verification steps, and transfer relevant information to its LOS or customer database.
This can help reduce disconnected manual tasks and improve visibility into the verification process.
The platform can complement existing lending and banking systems rather than replacing applications responsible for other business functions.
Before selecting KYCPLUS or any other provider, an NBFC should confirm the precise capabilities available, integration requirements, security controls, pricing, service levels, and suitability for its regulatory obligations.
Basic identity verification is only one component of the customer lifecycle.
An NBFC may also need to manage customer information, supporting documents, verification outcomes, consent records, exception queues, internal approvals, and ongoing KYC updates.
If these activities are handled in separate systems, manual work may continue even after identity verification has been automated.
A connected KYC architecture can link:
Digital Application → KYC Verification → Document Management → Exception Review → Customer Database → LOS/LMS → Reporting and Audit Trail
This approach can create a more repeatable process across customer acquisition channels.
NBFCs should therefore evaluate the complete workflow when selecting the Best KYC Software for NBFCs in India rather than focusing only on document verification.
The future of KYC technology will likely involve deeper integration, better automation, and more connected customer lifecycle management.
APIs allow KYC capabilities to be embedded directly into digital lending and onboarding applications.
OCR and AI can help extract information, classify documents, and identify incomplete submissions.
Platforms can route applications based on configured rules and verification results.
4. Integrated KYC Lifecycle
Initial KYC, applicable CKYC processes, Re-KYC, document management, and reporting can be connected within a broader workflow.
Mobile-friendly interfaces and clearer instructions can reduce avoidable friction.
Dashboards and exception analytics can help NBFCs identify delays and improve internal processes.
As digital lending and financial services evolve, KYC software will become increasingly important to the operational infrastructure of NBFCs.
KYC is a fundamental part of customer onboarding for NBFCs. As financial services move toward digital applications and technology-driven lending, manual verification processes can become difficult to manage efficiently.
The Best KYC Software for NBFCs in India should help organizations collect customer information, process documents, perform supported verification checks, integrate with lending systems, manage exceptions, and maintain appropriate records.
Important features include digital onboarding, OCR, document verification, API integration, CKYC-related workflows where applicable, Re-KYC management, document storage, dashboards, and audit trails.
However, the right software must also fit the NBFC’s business model, technology infrastructure, customer volumes, security requirements, and regulatory obligations.
A structured vendor evaluation, integration assessment, pilot, and ROI review can help organizations make an informed decision.
Platforms such as KYCPLUS can support digital KYC and related workflows for financial institutions, depending on the implementation and required integrations.
Ultimately, the goal of adopting the Best KYC Software for NBFCs in India is to create a reliable, scalable, and secure customer verification process that supports efficient onboarding while preserving the controls required for the institution’s business.
Ans: The best solution depends on the NBFC’s business model, verification requirements, customer volume, integration needs, security expectations, and budget. NBFCs should compare capabilities, integration quality, exception handling, and implementation support before making a decision.
Ans: KYC software helps NBFCs digitize customer information collection, document processing, verification workflows, and record management. It can reduce repetitive manual work and improve operational visibility.
Ans: Important features may include digital onboarding, document verification, OCR, API integration, workflow automation, dashboards, audit trails, and exception handling. CKYC and Re-KYC capabilities may also be relevant depending on the institution’s requirements.
Ans: Yes. Many KYC platforms provide APIs or other integration methods that allow them to exchange relevant information with an LOS. The exact integration depends on the systems involved and the provider’s capabilities.
Ans: OCR extracts supported information from document images and reduces manual data entry. The extracted information can be validated and routed through the configured verification process.
Ans: Some platforms support CKYC-related workflows and Re-KYC management. NBFCs should verify the exact functionality and ensure that it supports their applicable processes and authorized access arrangements.
Ans: Yes. Digital lenders can use KYC software to manage identity-related onboarding steps and transfer relevant results to their lending systems. KYC verification remains separate from credit underwriting and loan approval.
Ans: It can be suitable when the deployment model meets the institution’s security, data-handling, infrastructure, contractual, and applicable regulatory requirements. Each NBFC should assess these factors before choosing cloud deployment.
Ans: Pricing varies by provider, verification volume, feature set, integrations, deployment model, and support requirements. NBFCs should request a detailed quote that includes setup, transaction, subscription, integration, and ongoing support costs.
Ans: An NBFC should define its requirements, compare verification capabilities, evaluate APIs and security, test the software through a pilot, review the total cost of ownership, and confirm that the provider can support its implementation and operational needs.
