 Blog
Centralized KYC Software for Banks: A Complete Guide to Digital Customer Verification and Management
Blog
Centralized KYC Software for Banks: A Complete Guide to Digital Customer Verification and Management
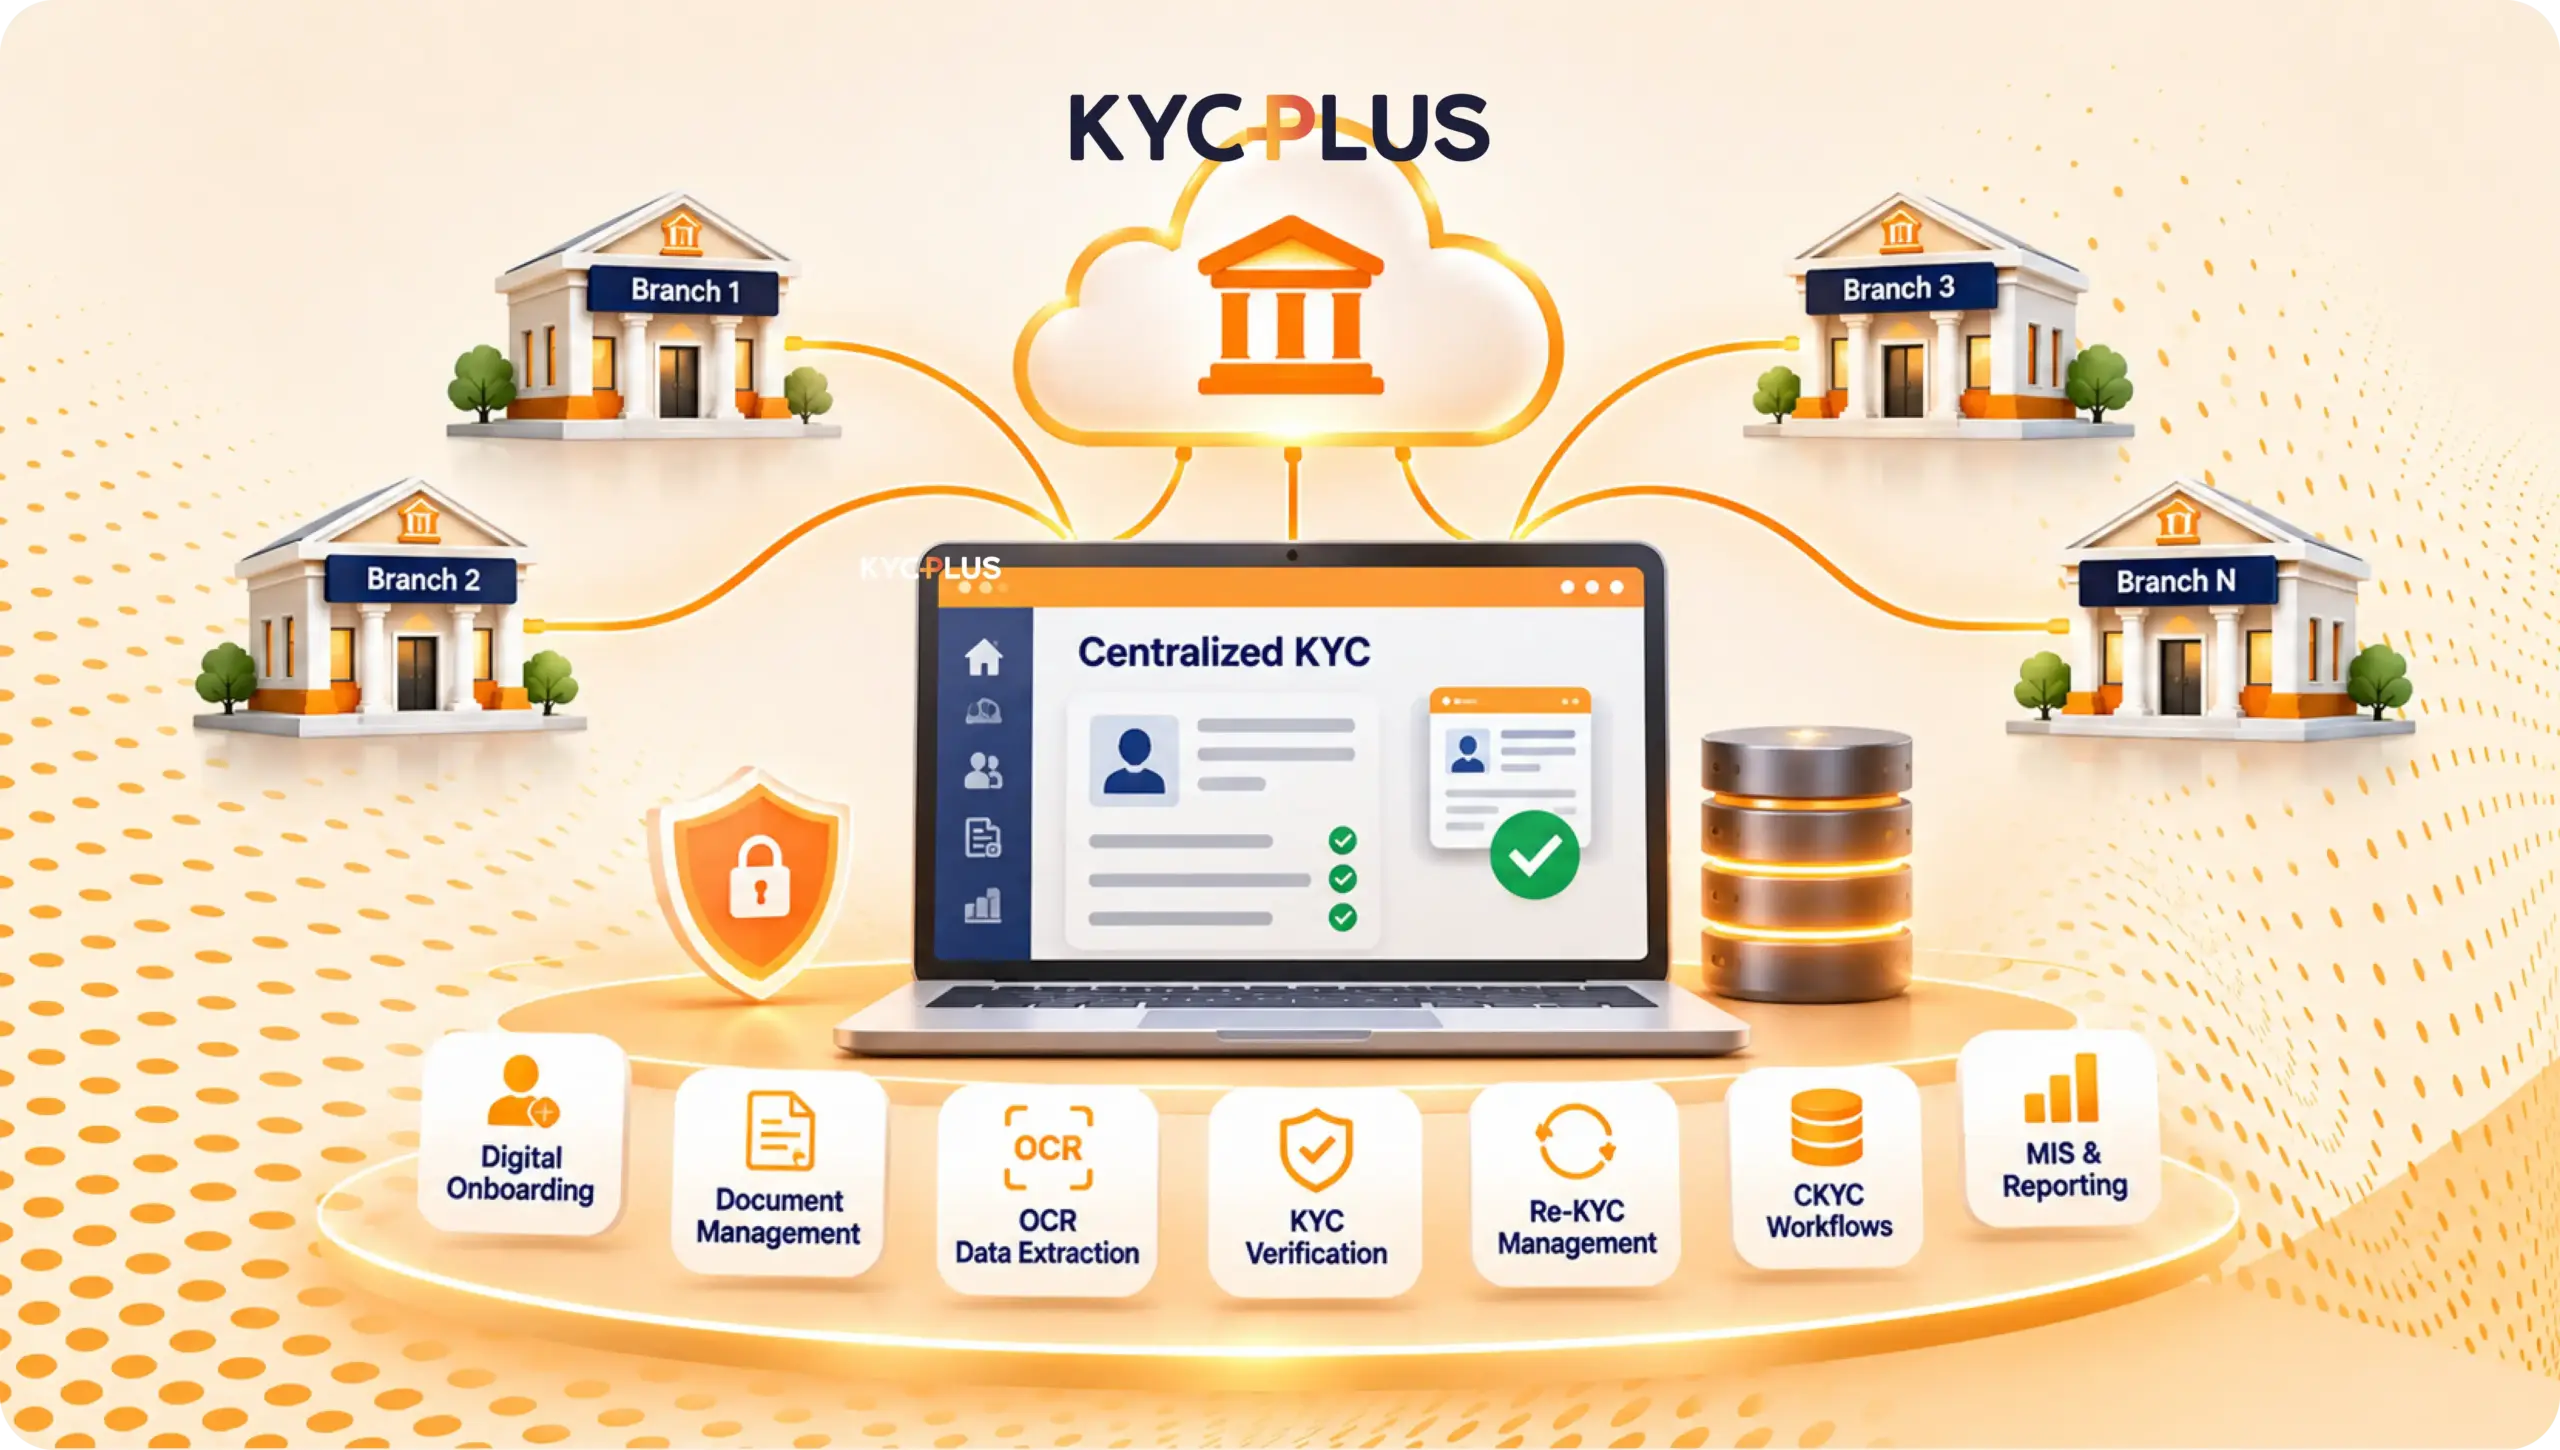
Banks manage a large volume of customer information every day. From opening new accounts and verifying customer identities to updating existing records and managing regulatory documentation, Know Your Customer (KYC) activities are an essential part of banking operations. As banking networks expand, implementing Centralized KYC Software for Banks becomes increasingly important for managing customer KYC information across multiple branches. It helps streamline access to customer records, standardize verification processes, reduce document management challenges, and enable management to access consolidated customer information efficiently.
Traditional KYC processes often depend on branch-level document collection, manual data entry, physical files, and separate customer records. These processes can create operational inefficiencies, increase employee workload, and make it difficult to maintain consistent information across the institution.
A centralized digital KYC platform provides a structured approach to managing customer verification activities. It allows authorized employees to access customer records, manage documents, track verification status, and coordinate KYC operations through a common platform.
With the help of automation, document intelligence, OCR, digital onboarding, and system integration, banks can improve how they manage customer information throughout the customer lifecycle.
For cooperative banks, Urban Cooperative Banks (UCBs), District Central Cooperative Banks (DCCBs), commercial banks, and other financial institutions, adopting Centralized KYC Software for Banks can help establish more organized and consistent KYC operations.
In this guide, we will explore what centralized KYC software is, why banks need it, its essential features, operational benefits, implementation considerations, and how digital platforms such as KYCPLUS can support centralized KYC management.
Centralized KYC Software for Banks is a digital platform that enables banking institutions to manage customer identification, verification, documentation, and KYC-related information through a centralized system.
Instead of maintaining disconnected KYC records at individual branches, banks can use a common digital platform to organize customer information and verification activities.
For example, consider a cooperative bank operating through 25 branches.
Under a traditional branch-based process, each branch may maintain its own customer documents, verification registers, spreadsheets, and KYC records.
When a customer visits another branch, employees may need to request information from the original branch or search through different systems to access the required documents.
With centralized KYC management, authorized employees can access relevant customer information through a common platform, subject to role-based permissions and institutional policies.
A centralized KYC platform can support activities such as:
The objective of Centralized KYC Software for Banks is not simply to store customer documents in one location. It is to establish a consistent process for managing customer information across the banking organization.
It is also important to understand that centralized KYC software is not the same as the Central KYC Records Registry (CKYCR). CKYCR is the centralized KYC record repository operated under the applicable regulatory framework. A bank’s KYC software can support its internal KYC operations and authorized CKYC workflows, but it does not replace the official registry.
Banking operations have become increasingly digital. Customers expect faster account opening, convenient document submission, and consistent services across branches.
At the same time, banks must maintain accurate customer information and follow applicable KYC requirements.
Managing these activities independently at every branch can create several challenges.
A centralized KYC platform helps institutions establish common processes and improve operational visibility.
Banks with multiple branches often maintain large customer databases.
When customer records are managed separately, employees may face difficulties accessing updated information.
A centralized KYC system helps bring relevant customer records into a common digital environment, making information easier to retrieve for authorized users.
Physical documents and scattered digital files can make customer document retrieval time-consuming.
Employees may need to contact another branch or search through multiple folders to find a particular document.
Centralized KYC document management helps organize customer documents and makes them accessible through a structured system.
Without a consistent process, customers may experience repeated document collection and verification activities.
A centralized customer profile can help employees identify existing customer information and relevant verification records, subject to the institution’s policies and applicable requirements.
Management needs to understand the status of KYC activities across the entire organization.
Separate branch-level spreadsheets and reports make consolidated monitoring difficult.
Centralized KYC software can provide dashboards showing customer verification status, pending cases, completed cases, and branch-level performance.
Manual data entry, document sorting, verification, and reporting consume valuable employee time.
Automation can reduce repetitive activities and help employees focus on document review, customer assistance, and cases requiring additional attention.
Different branches may follow different operational practices.
A centralized platform can provide standardized workflows, document requirements, user permissions, and approval processes across branches.
This helps banks establish more consistent KYC operations.
Understanding the workflow is important before implementing CBS Software for Banks.
A typical centralized KYC process involves several connected activities, starting from customer onboarding and continuing through document management, verification, and periodic information updates.
The process begins when a new customer applies to open an account or an existing customer needs to update their information.
Customer details can be collected through branch employees, digital onboarding channels, or supported integrations.
The information may include:
After collecting customer information, the required documents are uploaded to the platform.
Depending on the institution’s process, documents may include officially valid documents, address proof, photographs, and other applicable records.
A centralized platform associates documents with the relevant customer profile.
This reduces dependence on scattered physical files and helps employees retrieve information more efficiently.
Modern KYC platforms can use Optical Character Recognition to extract information from supported document images and PDFs.
For example, OCR can help identify customer names, document numbers, addresses, and other relevant fields.
Extracted information can then be compared with the information entered by the customer or employee.
Employees should review extracted information and resolve mismatches before completing the required verification.
The collected information and documents are reviewed according to the bank’s approved KYC process.
Depending on the customer category and applicable requirements, verification may involve document checks, additional identification methods, or employee review.
The platform can support configured workflows and record the status of each verification activity.
After the required process is completed, customer information and associated documents can be maintained within a centralized customer profile.
Authorized employees can retrieve relevant records according to their access permissions.
This helps reduce duplication and provides a more structured view of customer information.
Where applicable, the bank can use the platform to support its authorized CKYC-related activities.
This may include preparing customer information, manage documents, and facilitate submission or retrieval workflows through approved mechanisms.
The actual CKYC process must follow the applicable CERSAI and regulatory procedures.
Customer information may change over time.
A centralized platform can help banks identify records requiring updates, collect revised information, manage documents, and track Re-KYC progress.
This is particularly useful for institutions with large customer databases.
The platform can provide reports on customer records, verification status, pending activities, and branch-level performance.
Activity logs can help authorized users review changes and verification actions performed during the process.
Choosing the right platform requires evaluating its features against the bank’s operational requirements.
A suitable Centralized KYC Software for Banks should support customer information management, document processing, verification workflows, system integration, and reporting.
The following features are especially important.
A centralized customer database allows banks to manage customer profiles through a common digital platform.
Instead of maintaining separate records in different branch-level systems, relevant customer information can be organized in one environment.
Important capabilities include:
This helps authorized employees access relevant customer information without depending entirely on manual communication between branches.
Digital onboarding helps banks collect customer information and documents through a structured digital process.
Customers can submit their information through supported channels, while employees can review applications and manage verification activities.
A digital onboarding module can support:
Digital onboarding can reduce paperwork and create a more organized account-opening experience.
OCR is an important feature of modern KYC platforms.
It helps extract relevant information from customer documents and reduces the need for employees to enter every field manually.
Document intelligence can support document classification and information extraction, depending on the available technology.
Banks should evaluate:
OCR should assist the verification process, not replace the bank’s responsibility to verify customer information.
A Document Management System (DMS) helps banks organize customer documents in a structured digital repository.
Documents can be associated with individual customer profiles and retrieved by authorized users.
Useful DMS capabilities include:
A centralized DMS is particularly useful for banks managing large volumes of customer records.
CKYC is an important part of the customer verification ecosystem in India.
A centralized KYC platform can help banks manage their internal CKYC workflows and facilitate authorized interactions with the Central KYC Records Registry.
Depending on the platform’s capabilities, this may include:
Banks should confirm the exact integration and processing capabilities available in the selected solution.
Re-KYC is an ongoing requirement for maintaining updated customer information according to applicable regulations and the bank’s policies.
Centralized KYC software can help banks manage Re-KYC activities through digital workflows.
Useful capabilities include:
This helps banks manage customer information updates across multiple branches.
Core Banking System integration is an important consideration for banks.
CBS manages banking operations such as accounts, deposits, transactions, and customer records.
KYC software supports customer verification, document management, and related workflows.
Integration between these systems can help exchange relevant information and reduce duplicate data entry.
Before implementation, banks should evaluate API availability, data mapping, permissions, security, and update procedures.
Some digital onboarding workflows may require additional identity verification capabilities.
Face matching can compare a customer’s live photograph with an available reference photograph.
Liveness detection can help assess whether a submitted face capture represents a live person rather than a static photograph or other presentation.
The use of these capabilities should depend on the institution’s approved verification process and applicable requirements.
A centralized platform should allow banks to define access according to employee responsibilities.
For example:
Role-based permissions help protect customer information and support internal controls.
A reliable KYC platform should maintain relevant records of activities performed within the system.
These may include:
A centralized activity history helps institutions review operations and support internal audit requirements.
Management needs a clear view of KYC operations.
A dashboard can display:
MIS reporting helps management identify operational gaps and monitor progress.
API-based integration enables the KYC platform to exchange information with other banking applications.
This can support connections with CBS, CRM, LOS, LMS, and other relevant systems.
Banks should evaluate API documentation, authentication methods, data security, error handling, and integration support.
Implementing Centralized KYC Software for Banks can provide operational benefits across different departments and branches.
The following are some of the major advantages.
Centralized customer profiles help banks organize KYC information and related documents in a common environment.
This improves information accessibility for authorized employees and reduces dependence on disconnected records.
Automation can reduce repetitive activities such as document sorting, data entry, and manual status reporting.
Employees can spend more time on customer support and cases requiring additional review.
A common platform allows different branches to follow standardized workflows.
Centralized visibility can help head-office teams monitor activities and coordinate with branches more effectively.
A digital document management system helps employees retrieve relevant customer records without searching through multiple physical files or folders.
This can improve internal response times.
Banks can organize Re-KYC activities through centralized workflows, track pending cases, and monitor customer responses.
This becomes particularly useful when dealing with large customer databases.
Standardized forms, validation rules, document categories, and approval workflows help establish consistency across branches.
This can reduce differences in how routine KYC activities are managed.
Centralized dashboards provide management with an overview of operational performance.
Branch-wise and status-wise reporting can help identify pending activities and allocate resources appropriately.
Digital records, activity logs, and structured document storage can make it easier for authorized teams to retrieve information during internal reviews and audits.
Digital onboarding and organized document collection can make KYC interactions more convenient for customers.
A well-designed process can reduce unnecessary visits and repeated document requests where permitted.
As banks expand their customer base or open new branches, their KYC management requirements also increase.
A scalable centralized platform can support additional customers, branches, employees, and workflows.
Cooperative banking institutions have specific operational requirements.
Many cooperative banks operate through multiple branches and serve different categories of customers, including individuals, businesses, members, and other account holders.
Managing KYC records across these branches can become challenging without centralized systems.
Cooperative banks can use centralized KYC management to organize customer records, digital documents, onboarding workflows, and Re-KYC activities.
It can help head-office teams monitor branch-level operations through common reporting.
UCBs manage customers across savings accounts, current accounts, business relationships, and other banking services.
A centralized platform can help standardize customer verification and document management across branches.
DCCBs may coordinate operations across multiple branches and geographical areas.
Centralized KYC software can help consolidate relevant customer information and improve visibility into KYC activities across the institution.
Institutions operating across multiple states may face additional coordination requirements.
A centralized digital platform can help manage customer information, document records, and verification workflows through a common system.
NBFCs and other financial institutions can also use centralized KYC management, depending on their regulatory framework and business requirements.
Their platforms may need to integrate with lending, customer servicing, and other internal applications.
Selecting the right solution is an important technology decision.
Banks should not evaluate software only on the basis of its feature list. They should also consider implementation, security, integration, scalability, and long-term operational support.
Start by identifying the institution’s existing KYC challenges.
Consider:
This helps define the actual scope of the solution.
The platform should support structured customer profiles and allow authorized users to retrieve relevant information across branches.
Banks should evaluate search functionality, duplicate identification, record history, and customer data management.
A platform should support the KYC-related workflows relevant to the bank.
Institutions should confirm which CKYC activities are supported, whether bulk processing is available, and how Re-KYC workflows are configured.
Check whether the platform can integrate with the existing Core Banking System.
Discuss technical feasibility, APIs, data mapping, testing requirements, and responsibility for integration maintenance.
Customer KYC information requires strong security controls.
Evaluate encryption, user authentication, role-based access, audit logs, backup arrangements, and applicable data protection requirements.
The software should provide meaningful operational reports for branch managers, head-office teams, and administrators.
Reporting should support the bank’s actual monitoring requirements.
Banks may have different technology preferences.
Depending on the institution and provider, deployment options may include cloud-based SaaS or on-premise infrastructure.
Evaluate hosting, data residency requirements, access controls, maintenance, backup, and disaster recovery arrangements.
The software provider should understand financial-sector workflows and be able to support implementation, configuration, training, and ongoing maintenance.
Banks should also review the vendor’s integration experience and service-level commitments.
A pilot implementation can help validate the solution before organization-wide deployment.
Start with selected branches or a limited customer segment, review the results, and address any operational gaps.
A structured implementation approach helps banks avoid unnecessary disruption to their existing operations.
The implementation team should understand the bank’s customer management process, KYC workflows, branch structure, and technology infrastructure.
Existing customer records should be reviewed for duplicates, missing fields, incorrect formats, and outdated information.
The platform should be configured according to the bank’s operational requirements.
This may include customer categories, document types, user roles, verification stages, and approval workflows
The KYC platform can be integrated with relevant systems such as CBS and document repositories, depending on technical feasibility.
Where required, existing customer information and digital documents can be migrated according to an approved data mapping and migration plan.
Data accuracy should be checked before production use.
Employees should be trained to manage customer profiles, review documents, process applications, and monitor reports.
The solution should be tested with selected users and branches.
Testing should cover customer search, document uploads, verification, permissions, integrations, reporting, and exception handling.
After successful pilot validation, the solution can be rolled out across additional branches according to the bank’s deployment plan.
After deployment, banks should monitor system performance, employee adoption, customer experience, integration reliability, and workflow effectiveness.
Centralized KYC systems manage sensitive customer information. Therefore, security and compliance should be key considerations during software selection and implementation.
Banks must follow applicable KYC directions and other regulatory requirements.
For Indian banks, relevant RBI KYC directions and applicable CERSAI CKYCR procedures should be considered.
Software should be configured to support the bank’s approved processes.
Customer information and documents should be protected through suitable security controls.
These may include encryption during transmission and storage, secure authentication, and controlled access.
Access to customer information should be limited according to employee responsibilities.
This reduces unnecessary access and helps support internal governance.
The platform should maintain appropriate records of user activities, customer information changes, document handling, and verification actions.
Banks should establish appropriate document retention and deletion procedures in line with applicable legal, regulatory, and internal requirements.
Financial institutions should assess backup frequency, recovery procedures, infrastructure availability, and disaster recovery arrangements.
Banks should evaluate the service provider’s security controls, operational processes, contractual obligations, and incident management procedures.
Managing customer verification across multiple branches requires a platform that can support more than basic document storage.
Financial institutions need a solution that brings together customer onboarding, KYC workflows, CKYC-related activities, Re-KYC, document management, and integration capabilities.
KYCPLUS by Azlogics is a digital KYC platform designed to support banks, cooperative banks, UCBs, DCCBs, NBFCs, and other financial institutions.
It offers capabilities that can help institutions organize their KYC operations through digital workflows.
KYCPLUS supports digital customer onboarding workflows that help institutions collect customer information and documents through a structured process.
The platform can help organize customer KYC information and verification activities through a common application, subject to configured access permissions and workflows.
KYCPLUS supports CKYC-related workflows to help financial institutions manage relevant customer information and documentation activities through configured processes.
The platform supports Re-KYC workflows that can help institutions manage customer information updates and related verification activities.
OCR and document intelligence capabilities help extract information from supported customer documents and reduce repetitive manual data entry.
KYCPLUS provides document management capabilities to help organize customer documents and make them accessible to authorized users.
Integration capabilities can help connect KYCPLUS with existing banking infrastructure, depending on the bank’s technical environment and agreed scope.
Digital activity tracking and centralized monitoring can help institutions review workflow progress and maintain relevant operational records.
For banks evaluating Centralized KYC Software for Banks, KYCPLUS can be considered as a platform for organizing digital KYC operations. The appropriate modules, integrations, and deployment model should be finalized after understanding the institution’s specific requirements.
The banking industry is moving towards more connected and technology-driven operations.
As customer expectations increase and banking networks expand, centralized customer information management will become increasingly important.
Several developments are likely to influence the future of centralized KYC systems.
AI can support document classification, information extraction, and identification of incomplete or inconsistent records.
This can help employees process customer information more efficiently.
API-based integrations will help connect KYC applications with CBS, CRM, LOS, and other systems.
This can improve data exchange and reduce repetitive manual work.
Customers will increasingly expect convenient digital onboarding experiences.
Banks may continue adopting technologies that simplify information collection and verification while maintaining required controls.
Document intelligence can help identify document types, extract relevant fields, and support quality checks.
This may improve the efficiency of document management workflows.
Management teams will continue to require real-time or near-real-time visibility into operational activities.
Centralized dashboards and reporting tools can support better monitoring and decision-making.
As more customer information is managed digitally, security, privacy, access governance, and data protection will remain essential considerations.
The future of Centralized KYC Software for Banks will depend on the ability to combine automation with secure information management, effective verification controls, and a convenient customer experience.
Managing customer KYC information across multiple branches is an important operational responsibility for banks. Traditional branch-level processes can create challenges related to document storage, customer information access, repetitive verification, and management reporting.
Centralized KYC Software for Banks provides a structured way to manage these activities through a common digital platform.
With capabilities such as centralized customer profiles, digital onboarding, OCR-based document processing, CKYC workflow support, Re-KYC management, document management, CBS integration, and audit trails, banks can improve the organization of their KYC operations.
For cooperative banks, UCBs, DCCBs, and other financial institutions, centralized KYC management can help improve branch coordination and operational visibility.
However, choosing the right software requires careful evaluation of regulatory requirements, system compatibility, data security, scalability, and implementation support.
Platforms such as KYCPLUS by Azlogics can support financial institutions in building more organized digital KYC workflows.
As banking operations continue to evolve, adopting the right Centralized KYC Software for Banks can be an important step towards more efficient customer information management and digital banking operations.
Ans: Centralized KYC software for banks is a digital platform that helps banking institutions manage customer identification, verification, documents, and KYC-related information through a common system. It supports consistent KYC workflows across multiple branches.
Ans: Banks need centralized KYC software to organize customer records, improve document accessibility, reduce repetitive manual activities, monitor verification progress, and establish consistent KYC processes across branches.
Ans: It collects customer information and documents, supports data extraction and verification workflows, maintains centralized customer profiles, and provides reporting and monitoring capabilities for authorized employees.
Ans: Yes. Depending on the technology architecture and available interfaces, centralized KYC software can integrate with a Core Banking System through APIs or other supported integration methods.
Ans: Yes. Cooperative banks can use centralized KYC software to organize customer information, manage documents, monitor branch-level activities, and support digital onboarding and Re-KYC workflows.
Ans: Centralized KYC generally refers to managing customer KYC information through a common internal system within a bank or institution. CKYC refers to the Central KYC Records Registry framework in India, which maintains centralized KYC records for authorized institutions.
Ans: Yes. A centralized KYC platform can support Re-KYC workflows by helping banks identify records requiring updates, collect documents, manage verification activities, and monitor completion status.
Ans: It can reduce repetitive activities through features such as OCR, digital document collection, automated workflows, centralized search, and reporting. Employee review and approval remain necessary where required.
Ans: Important features include centralized customer profiles, digital onboarding, OCR, document management, CKYC workflow support, Re-KYC management, CBS integration, audit trails, role-based access, and MIS reporting.
Ans: It helps branches access relevant customer records through a common system, follow standardized workflows, manage digital documents, and monitor pending verification activities.